
Spread betting in the UK: where the market sits, what it costs, and who is licensed to take it
 Available in US
Spread betting is older than the online bookmaker it travels with now. Charles K. McNeil, a Connecticut maths teacher turned Chicago bookmaker, drew the first spread in the 1940s on American football. The form crossed the Atlantic into financial markets first, then into sport, and the split that followed still runs through every UK platform a punter looks at today: financial spread betting sits with the Financial Conduct Authority, and sports spread betting offered by a bookmaker sits with the Gambling Commission. Both ask the same two questions of the person staking the money — how much per unit, and how wrong are you willing to be.
30 October 2026 — checked against the Gambling Commission’s public register.
Predictions, forecasts and the bankroll behind them
A spread bet is a wager on accuracy, not on a winner. A punter who buys a cricket team’s runs at 350 and the team scores 400 wins 50 units times the stake; the same stake against a 300 total loses 50 units times the stake. Profit and loss both grow with the difference between result and bet level — the bookmaker’s spread sits in the middle. There is no version of this where the punter’s risk is capped at the stake on the betting slip, and there is no version where the cricket example is a one-off.
That asymmetry is why the search for “best bets against the spread”, “NFL spread picks” and “NBA spread tips” is a market of its own. The tipster industry built itself around predicting a margin of victory, because that margin — the score differential — is exactly what a spread asks for. A football spread might price Manchester City to win by 2.0–2.5 goals; an NBA spread might price the Lakers at -4.5; a tip pick is a number, not a winner. The tip is a forecast of distance, and the punt pays out only when that forecast is closer to the truth than the spread already on screen.
The same logic applies to any sport the bookmaker has priced. Football tipsters call goal differences. Cricket tipsters call innings totals. Horse racing tipsters call finishing margins, on a Total Goals or a Race Index market. The skill the punter is being paid for in each case is forecasting a continuous variable more accurately than the market has. Most tipsters sell the forecast, not the return — a tip service may have a winning record against the spread and still leave subscribers down, because the commission, the subscription and the losing months were never recovered by the winning ones at the price the punter took.
A bankroll plan matters more here than in fixed-odds betting for one reason. A fixed-odds loss is the stake; a spread loss is the stake times the wrong side of the prediction. A punter running 2% of bankroll per unit who is wrong by ten units has lost 20% of the bank — and that is one bet, with ten more fixtures waiting on the slip.
Strategies turn on sport. NFL and college football spread work is almost the whole North American market for the format, because the spread suits a sport decided by field position and points. Rugby, with its scoring bands, takes to spread betting cleanly on total points and handicap spread. Football in the UK settles on Total Goals markets (0–2, 3–5, 6+ and so on) and Supremacy spreads (how many goals the favourite wins by). Cricket settles on innings run spreads. Horse racing offers Race Index markets that bundle a runner’s beaten distance, prize-money position and finishing order into one price. The strategy question changes market by market, and the bankroll question stays the same.
Forecast skills transfer poorly between markets. A punter who reads NBA spreads well is starting from zero on a Super Over cricket spread, and a tipster service with a thousand NFL picks behind it has no edge at Aintree’s Race Index. The most common bankroll mistake in spread betting is to size a position by what the tipster’s record looks like on paper rather than by what the punter can lose on the next single result.
A bankroll frame that protects the punter in this format has three habits. Keep the per-unit stake small — research suggests fractional staking of 0.5% to 1% of bank per unit as a starting point, with the upper end reserved for markets a punter tracks daily. Track the result in units, not in pounds, so that a good week and a bad week show up on the same scale. Stop betting on a market where the punter cannot explain why the spread is wrong. A spread is the bookmaker’s view, and the punter is betting against a view, not against a number — a “this spread is too low” reason matters; a hunch does not.
Bet types and what they ask of the punter
A spread and a fixed-odds price do different jobs.
A fixed-odds bet asks a yes-or-no question: will the favourite win, will the total go over, will the home side cover the handicap. The price tells the punter how much a correct answer pays; the stake is the loss if the answer is wrong. The punter’s risk is capped at the stake by design.
A spread asks the same yes-or-no question, but the answer is on a scale, and the punter bets on where on that scale the answer will land. A “buy” at 350 runs means the punter bets the team will score more than 350; a “sell” means fewer. The stake is set per unit of distance from the spread. Profit grows with how right the punter is; loss grows with how wrong.
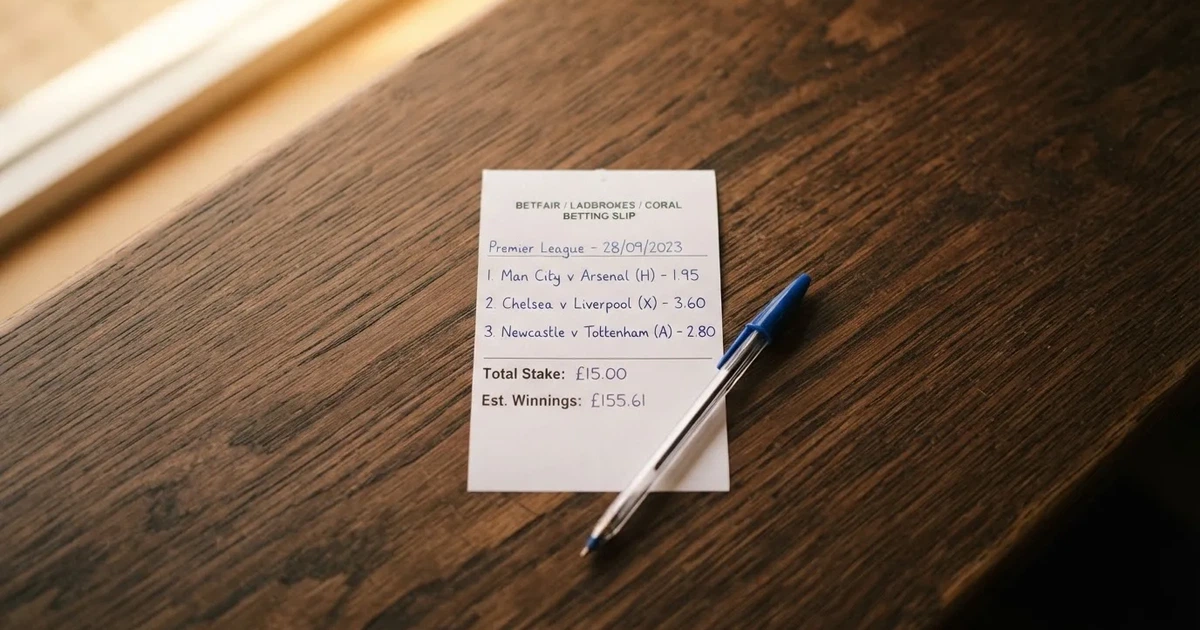
The asymmetry is the entire business. A £2-per-unit punt buying at 350 runs wins £100 if the team scores 400; it loses £100 if the team scores 300. The loss is not the stake — it is the stake per unit times how many units the result misses by. That mechanic is what makes spread betting so attractive to bookmakers and so punishing to the under-banked.
Three spread families cover almost everything a UK punter looks at. Total Goals markets on football price the goals in a match as a band (0–2, 3–5 and so on). Supremacy markets price the winning margin between two sides. Performance Index markets on cricket, rugby and racing bundle several outcomes into one spread — runs scored, wickets lost, points difference, beaten distance. Each family settles on a continuous number, not a win-or-lose flag.
The arithmetic of a winning spread bet is short and worth keeping in mind. A successful buy at 350 when the result is 400 pays 50 units times the stake — that is the (result minus buy price), which for a £2 stake is £100. A successful sell at the same spread when the team scores 300 pays the same, because the result falls 50 units below the sell. The bookmaker settles on the difference between result and the bet level, not on a binary outcome.
A losing spread bet is the same arithmetic, the other side of the line. Buy at 350, team scores 300: 50 units times the stake is owed to the bookmaker. Sell at 350, team scores 400: same loss. The punter loses the same amount whether the result missed the bet up or down; what matters is the distance, not the direction.
Side orders complicate this. Most sports bookmakers offer a “make the book” stop or a “guaranteed stop” on the spread, which caps a single bet’s loss at a fraction of the stake. The cap costs the punter a wider spread — the bookmaker takes its fee in points, not pounds. A cap that limits the loss on a single result to £50 might cost the punter a five-run spread on a cricket bet — buying at 345 instead of 350, with the same £2 stake.
Settling is where most spread beginners lose their footing. A spread bet does not know whether the punter is right at the moment the bet is placed; it only knows at settlement, when the event is over and the result is in. Any halfway score during the match — at 150 for 3 in a cricket innings, at 1–0 in football — does not settle the bet. That feature is why a spread can drift through several smaller intraday numbers before settling, and why a punter who cannot read the in-running state has no way to tell whether the bet is winning, losing, or still somewhere on the spread.
Some bookmakers offer an early-settle product: closing the bet at any point and taking the running profit or loss. The price quoted on the early settle is the bookmaker’s view of where the result will land, and it almost never favours the punter against an undecided result. Early settle is convenience — it caps a known loss or locks a known gain — not a way to out-trade the bookmaker.
Sports, tournaments and the fixtures that move the spread
Spread prices follow fixtures, and a fixture list that the bookmaker expects to draw money will get a tighter spread than one the bookmaker expects to leave sitting. Premier League fixtures, Champions League nights, the NFL slate on Sunday and Tuesday, the Grand National and Royal Ascot — these are where spread books are written, with the most interest, the smallest margins and the deepest markets.
Football is the largest spread market in the UK. The Premier League runs Total Goals, Supremacy and Corners spreads on every match; the Champions League gets the same products on bigger fixtures, with tighter spreads when the clubs are well known and looser ones when the line-ups are not. The Championship, the Scottish Premiership and the top European leagues are priced thinly on most UK platforms but always with a spread on Total Goals. Football tournaments with international sides — World Cup and Euro qualifiers, the Nations League — get spread coverage on the same markets. The pattern is consistent: the bigger the event, the tighter the price the punter sees.
American football takes to the spread naturally — it is the format’s home sport. NFL Sunday’s full slate is priced on most UK platforms, with point spread, total points and moneyline markets available. College football (NCAA) is sparser on UK sites but on most of them by the Conference Championship weekend. NBA is priced nightly from October through June, with the spread on the game handicap and the total points. The NHL has thinner spread coverage in the UK, and Major League Baseball has a small set of markets during playoffs, mostly on totals and run line.
Cricket gets spread pricing on international fixtures and on the larger domestic tournaments. Test match innings totals, ODI innings totals and the Hundred team totals are all spread markets on most UK sports bookmakers. T20 franchise leagues are priced on totals and on win-margin bands. Horse racing takes the format through Total Goals-style markets on the meeting, through Jockey Index on individual rides and through Race Index on finishing position, beaten distance and prize money rank. Greyhound racing follows the same shape.
Markets move with the fixture. A football spread published on Monday at 1.5–1.8 goals on Total Goals will move when team news lands, when weather forecasts shift and as the market digests money on either side. Spreads on events with team news closer to kick-off move further and faster than spreads on events with line-ups confirmed hours ahead. A punter who waits for the team sheet can sometimes get a price the early-morning market missed; a punter who waits into the match has missed the spread entirely on events the bookmaker closes early.
Tournaments drive volumes of money, and volumes drive the size of the spread. A punter looking at the Grand National needs only a small position to make the bet interesting — the spread is tight and the books are large — whereas the punter looking at a League Two fixture on a Tuesday night faces a wider spread and a smaller book. The size of the spread is the size of the bookmaker’s fee on the bet, and tournament events are cheaper to bet than off-piste fixtures.
In-running spread pricing exists on most major UK bookmakers’ sites for football, cricket and horse racing. A spread on a cricket match will move ball by ball on some platforms, with a Total Runs market that updates as the innings progress. In-running is a separate skill — the punter needs to track the game in real time and to read the bookmaker’s drift on the running spread. It is also where the punter is most exposed: a position taken into half-time with the score at 1–0 is settled at full-time, not at the moment the position was opened, and a half-time goal does not save a losing spread.
How a spread bet actually works
The simplest way to set out the market is in three steps.
First, the bookmaker publishes a spread. A Total Goals spread on a Premier League match might be 2.6–2.8 goals. The buy price is 2.8 (the punter thinks more goals will be scored than this), the sell price is 2.6 (the punter thinks fewer goals will be scored than this). The difference between buy and sell — here, 0.2 goals — is the bookmaker’s spread, which is how the bookmaker gets paid.
Second, the punter decides direction and stakes. “Buying” at 2.8 with a £2 stake says: more than 2.8 goals. “Selling” at 2.6 says: fewer than 2.6. The stake is set per unit of distance from the bet, not as a fixed bet amount. A £2 stake on this spread pays £0.40 for every 0.1 goals the result is away from the bet level.
Third, the fixture settles. The match finishes 3–1, four goals in total. The punter who bought at 2.8 with a £2 stake wins (4 − 2.8) × £20 = £24, because 1.2 goals above the bet level times the £20-per-unit distance is the return. The punter who sold at 2.6 with the same stake loses (4 − 2.6) × £20 = £28 — that is how much the bookmaker is owed. The mechanics are continuous. There is no rounding, no push and no cap on the result within the open market (unless a stop is in place).
In North American point spreads, by contrast, a result landing exactly on the spread is a push and the stake is refunded. The standard price on a point-spread bet is 10/11 — a bettor stakes £11 to win £10, which is a fee of roughly 4.5% on the bet. That price is the bookmaker’s margin. The push rule does not exist in UK sports spread betting, where any difference from the bet level settles at the stake per unit of distance.
A football spread punter is buying or selling on a price the bookmaker can move right up to kick-off. A point-spread punter in North American markets books a single price at one moment and the line moves around them but the price does not. The two formats look like the same product. They are not. Sports spread betting in the UK is a continuous settlement between a number on screen and the eventual result; the point spread is a wager on a fixed price against a moving number. Both are called “spread betting”. Both settle differently.
Three mechanics make UK sports spread unique. The first is the settlement window. A spread bet on a Saturday football match settles when the match finishes, not when the bet is placed; running positions can be checked on some platforms but the official settle only arrives at full-time. The second is the doubling that comes from continuous outcome: a £2 stake at a 0.2 spread is settled to the nearest unit the bookmaker prices, which usually means the punter’s liability is a small multiple of the stake rather than the stake itself. The third is the stake cap. Some spreads allow the punter to set a stop-loss and a stop-win before placing the bet, capping the loss on a wrong-way result, and most UK platforms do not cap liability until the punter sets one.
Making the bet on screen is the easy part. Choosing the stake and the direction is where it gets expensive. A punter with a £500 bank who takes a £2 stake on a 0.2 spread is staking £20 per unit of distance — that is 4% of bank per unit. If the result misses by ten units (a 2-goal drift on the 0.2 spread above), the punter loses £200 of bank on the one bet. A punter who cannot afford to lose that should not be in the market at that size, and the platform will not ask them to leave. The platform will let the punter place it.
Banking a position. Some platforms offer to “bank” a portion of a winning spread bet at half-time, locking in part of the profit before the result is in. The punter pays for that privilege in a wider spread (the trade) or in an explicit fee. It works best when the punter is right and the platform is willing to give up part of the position. It does not work as a substitute for sitting out uncertain matches.
Settling on cancelled fixtures. A football match abandoned at 1–0 with the spread at 2.6–2.8 is settled at half-time score on most UK platforms if the result does not stand. Spread bets are also made void if the event is cancelled. A cricket match reduced to fewer overs is usually settled on the reduced target. Platform rules differ — they are stated in the betting rules section of each operator’s site — and a punter with positions across several platforms should read each one rather than assume.
The ten UK platforms compared
The ten operators below are the brands a UK punter sees most often in side-by-side comparisons of licensed spread and fixed-odds products. Each is on the Gambling Commission’s public register against a remote general betting licence for real events; each takes part in GAMSTOP; each is subject to the same Advertising Standards Authority rules and the same 10x bonus cap that took effect on 19 January 2026. The table that follows summarises the headline points, and the write-ups that follow cover what the comparison cannot — what each operator’s terms look like in detail and where each one earns or loses the punter.
| Brand | Licence (account) | Licence holder | What the operator’s terms state |
|---|---|---|---|
| Spreadex | 008835-R-104580-022 (8835) | Spreadex Limited | Free bets usable across fixed odds and spread; qualifying bet must be placed within 28 days of opening the account |
| Sporting Index | 027343-R-308898-011 (27343) | Sporting Index Limited | Qualifying fixed-odds bet cannot be cashed out early or placed in play to unlock free bets and spread tokens |
| Coral | 054743-R-330863-014 (54743) | LC International Limited | Welcome free bets issued within 7 days and expire 7 days after issue; minimum odds apply on the qualifier |
| Sky Bet | 067370-R-341330-005 (67370) | SBG Sports Limited | Three £10 free bet tokens credited after a small first bet at minimum odds 1/1 |
| Dabble | 065677-R-340363-005 (65677) | Dabble Sports UK Ltd | Free bet stake not returned with a winning free bet; 7-day expiry |
| Swifty Sports | 058957-R-334734-006 (58957) | Swifty Global (UK) Ltd | Best Odds Guaranteed and Cash Out on racing and football; Bet Builder listed as coming soon |
| Betfred | 039544-R-319290-010 (39544) | Petfre (Gibraltar) Limited | Bet Builder, Extra Places and Sub Switch on the sports app |
| Lottoland | 038991-R-319408-020 (38991) | EU Lotto Limited | Sports book runs alongside the lottery and casino products |
| 888sport | 039028-R-319297-014 (39028) | 888 UK Limited | Cash Out, Bet Builder, daily boosted odds and racing streams on the app |
| VBet | 044662-R-324273-022 (44662) | SCGO Limited | Bet Builder, in-play pricing and a live calendar on the VBet app |
Spreadex is the only operator in the table that holds a dual licence. The firm sits with the Gambling Commission for fixed-odds sports and betting on real events, and with the Financial Conduct Authority for financial spread betting, which is the more demanding of the two regimes on capital, conduct and reporting. Both are checked on the regulator’s public register. The cost of this dual status surfaces in the welcome offer: £60 in free bets for a £10 fixed-odds bet, with the free bets usable across both fixed-odds and spread products and a 28-day window to place the qualifying bet. The products on the site are the spine of a UK sports spread bettor’s day — Total Goals on the Premier League, Race Index on the weekend racing, Supremacy on the Champions League nights — and the firm’s own headline is that spread betting losses can exceed deposits. Where Spreadex earns the punter is in the breadth of the spread book: football, horse racing, cricket, golf and rugby all get priced. Where it loses the punter is the same breadth on the wrong fixture — a League One midweek match will get a tighter spread at Coral or Sky Bet than at Spreadex, because Spreadex’s book on smaller fixtures is shallow. Worth it for the punter whose fixture list runs through major meetings and Premier League weekends, less so for the punter living on Tuesday night Championship football.
Sporting Index is the second of the two gambling-only spread specialists on the list. The welcome offer is more involved than Spreadex’s: a £10 fixed-odds bet at minimum odds of 1/2 (1.50 in decimal) unlocks three £10 fixed-odds free bets, three £5 Total Goals spread bets, three £5 Winning Favourites spread bets and a £1 Race Index spread bet. The qualifier cannot be placed in-play and cannot be cashed out early — the punter has to leave the bet on. That is a load-bearing condition: it rules out the matched-betting play some readers will recognise. What it gets in return is a single account that puts a foot in fixed-odds, Total Goals, Winning Favourites and Race Index betting on day one — four legs of the spread betting market under one roof. The firm sits under Sporting Index Limited. Worth it for the punter who wants to try four spread families at once; less so for the punter whose betting is on a single sport.
Coral is a fixed-odds bookmaker first. The welcome structure is “Bet £20, Get £40” in free bets: a £20 deposit and sports bet at minimum odds of 2.0 unlocks £40 in free bets issued within seven days and expiring seven days after that, on a 7-day clock twice over. Coral is the longer-established brand of the Ladbrokes-Coral group under LC International Limited. The firm does not lead on sports spread betting the way Spreadex and Sporting Index do — Total Goals and Supremacy are priced on the headline events and gone on most weekday fixtures — but the fixed-odds side is broader, with Best Odds Guaranteed, Extra Places and a deep market on Premier League and Championship football. Worth it for the punter whose spread interest is weekend football only and whose main book is fixed-odds; less so for the punter living on the spread book day to day.
Sky Bet is the SBG (Sky Betting and Gaming) side of the comparison, under SBG Sports Limited. The welcome is small and fast: £30 in free bets as three £10 tokens after a £5 deposit and a first single or each-way bet of 5p at minimum odds of 1/1. The structure is low-friction and aimed at the casual punter more than the spread specialist. The bookmaker offers Best Odds Guaranteed, Acca boosts and a long list of boosted-odds markets, and the spread book on the football side runs Total Goals and Supremacy on most Premier League and EFL fixtures. The Sky Bet look is mobile-first and the app is well-regarded. Worth it for the casual punter who wants a low-cost entry point and the brand recognition; less so for the spread punter because the spread book is shallower than Spreadex’s and not deeper than Sporting Index’s.
Dabble sits on Dabble Sports UK Ltd and runs a different kind of welcome: Bet £10, Get £10 in Free Bets, on a first deposit, with a 7-day free bet expiry and the free bet stake not returned on a winning free bet. That last condition is the cost. A £10 free bet at evens (2.0) returns £10 of profit, not £20 of return — the stake is gone after the bet is placed. The firm’s USP is a social-betting layer where punters can follow and copy each other’s bets. Worth it for the punter whose betting is light, occasional and social; less so for the punter who is sizing positions on the spread book daily, because the social layer does not replace the missing spread book on anything but the major events.
Swifty Sports runs a thin, focused sports book under Swifty Global (UK) Ltd. Best Odds Guaranteed, Cash Out on racing and football, daily price boosts, live streaming and in-play pricing are listed; Bet Builder is flagged as coming soon. The welcome offer is not in this bank, which is itself a signal: Swifty is competing on the quality of the fixed-odds book rather than on the headline free-bet. The spread book is small — Total Goals on Premier League and Championship fixtures, Supremacy on the headline matches. Worth it for the punter whose betting is racing-led and whose spread book is football-only; less so for the spread punter across sports, because Swifty does not price cricket, rugby or racing with a spread.
Betfred is the established bookmaker side of the comparison, under Petfre (Gibraltar) Limited. The app carries Bet Builder, Sub Switch (Sub On / Sub Off on selected markets), Racing Post data, Extra Places, live casino and bingo. The fixed-odds book is broad; the spread book is essentially football-led, with Total Goals and Supremacy on Premier League and Championship fixtures. Welcome offer details are not in this fact bank — the firm’s headline is the breadth of the fixed-odds book, the Sub Switch feature for football team-news punters, and the racing extras. Worth it for the punter whose betting is football, horse racing and bingo-led; less so for the spread punter looking past football.
Lottoland is the lottery product first, with sports and casino under the same licence (EU Lotto Limited). The spread book on football is small but present; the headline offers are on the lottery product (betting on the outcome of international lotteries) and on scratchcards. Sports spread betting on Lottoland is a side product. Worth it for the punter who wants a multi-product account under one login; less so for the punter whose betting is sports-first, because the spread book is the smallest of the ten.
888sport carries Cash Out, Bet Builder, racing streams, BetFinder form tools, a live bet feed and daily boosted odds under 888 UK Limited. The fixed-odds book is broad and the spread book is football-led. The headline feature is the racing streams — live racing across the day, paired with Best Odds Guaranteed and form data. Worth it for the punter whose betting is racing-led and who likes a streamed, in-running fixed-odds book; less so for the spread punter because the spread book is football-only.
VBet publishes the Vbet app under SCGO Limited. The bookmaker carries Bet Builder, pre-match and in-play pricing, live streaming and a live calendar with results and statistics. The spread book is essentially Premier League and Champions League football. The welcome offer details are not in this fact bank — the firm’s headline is the breadth of in-play products and the live calendar. Worth it for the in-running punter whose betting is football-led; less so for the spread punter across sports, because the spread book is the smallest of the three sports-led bookmakers.
A practical way to choose between these ten. Pick Spreadex or Sporting Index if the spread book itself is the day; pick Coral, Sky Bet, Betfred or 888sport if the fixed-odds book is the day and the spread book is a Saturday afternoon interest; pick Dabble and Swifty if the betting is light and casual; pick Lottoland and VBet for the multi-product or in-running-led punter. The punter with a fixture list running through every sport on the calendar has a narrower choice than the punter with a single sport on the slip.
The Gambling Commission’s register is the test of each of these licence numbers. A punter who checks the licence number against the register sees the licensee name, the licence categories held, any regulatory action on record and the current status. That check takes a minute. It is the single test of any UK-licensed bookmaker.
Where spread betting sits in the UK market
Spread betting is one of two formats on a UK sports bookmaker’s site, and it is the older one in spirit. A punter on a Premier League Total Goals market can bet the spread, with a stake set per unit of distance from the line, or bet the fixed-odds totals (over 1.5 at 2/5, over 2.5 at evens, over 3.5 at 3/1 and so on). The two formats price the same event differently. The fixed-odds price says “three goals or more returns two-to-one on a £2 stake”. The spread price says “buying at 2.8 means more than 2.8 goals; selling at 2.6 means fewer; the gap is the bookmaker’s fee”. The punter comparing the two is comparing two different risk profiles for the same question.
The fundamental difference is in the loss. A fixed-odds total-goals bet loses the stake if the answer is wrong. A spread bet on the same total-goals market can lose more than the stake if the result misses by more than the bookmaker’s spread, and the loss is the stake per unit of distance. The risk asymmetry is the whole reason spread betting is its own product. The fixed-odds book is sold to customers who want to know their max loss. The spread book is sold to customers who want a price closer to the true line and are willing to accept that the loss is on a scale, not on a flag.
Spread betting is also where the bookmaker’s margin can be smallest on the major events. A Premier League Total Goals spread might run 2.6–2.8 on a Saturday match — a margin of around 4%. The same match’s fixed-odds over-2.5 market might be priced closer to 1.85/1.85, a margin of just over 8%. The spread is the cheaper bookmaker’s fee on that fixture. The cheaper fee is also the larger loss-cap.
The bookmaker’s margin in a continuous market like spread betting is harder to read than in a binary market like fixed-odds. A binary market has two prices — back and lay, or over and under — and the margin is the difference between one minus the sum of the implied probabilities. A continuous market has a buy price and a sell price, and the margin is built into the gap between them; the punter’s cost of betting is the gap itself. A 0.2 spread on Total Goals is a wider bookmaker fee than a 0.1 spread; a 0.1 spread is the same product with the bookmaker paying itself less per bet.
A bookmaker’s margin in a single illustration makes the point. Take an illustrative two-way market priced at decimal odds 1.90 / 1.90 (fractional 9/10 each side). The implied probability on either side is 1 / 1.90 = 52.63%. The two prices imply a total probability of 105.26%, which means the bookmaker’s margin is 5.26%. The punter gets back, on average, 94.74 pence of every pound bet on this market. The rest is the bookmaker’s fee on the bet. The same fee structure built into a 0.2 goal spread is implicit: the punter’s effective cost of betting is 0.1 goals on either side of the true line, and the 0.2 spread is the bookmaker’s margin on the bet.
That margin shrinks with the size of the event and grows with the size of the firm’s book on the event. A bookmaker writing many sports books on a Premier League match can afford a tighter spread than one writing a single position on the same match, because the bookmaker with the bigger book can absorb a winning punter on the other side. Tournament events — the Premier League, the Champions League, the World Cup, the Grand National — are tighter than off-piste events, because the books are larger.
The “landscape” of the UK sports spread market is dominated by two firms in the spread-specialist sense — Spreadex and Sporting Index — and by the spread books on the larger sports bookmakers’ sites (Coral, Sky Bet, Betfred and so on) for the punter whose betting is across formats. The punter with a serious spread position on the All-Ireland hurling final will not find a price on the eight smaller bookmakers in the table; the punter with a spread position on a Premier League Saturday match can take her pick. That asymmetry runs through the entire UK market.
Where the spread book is missing, the firm offers fixed-odds. Coral does not lead on cricket spread, but Coral’s fixed-odds cricket book is large. VBet’s spread book is football-only, but VBet’s in-running fixed-odds book is wide. The firms that do not run a spread book at all are outside this list. The ten operators above are the brands that hold the Gambling Commission’s remote licence and offer at least some spread book on the major football fixtures.
Where a UK punter who wants a serious spread book will land most of the time is on the two spread specialists. Spreadex and Sporting Index run Total Goals and Supremacy on football, Race Index on horse racing, Jockey Index on individual rides and Performance Index markets on cricket and rugby. They take positions on the same events as the larger bookmakers but with the spread book as the main product, not a side product. The fee structure differs accordingly.
The legal frame for spread betting in the UK
Spread betting in the UK sits across two regulators and one law for the act of placing the bet itself. The Gambling Act 2005 covers Great Britain — England, Scotland and Wales — and is administered by the Gambling Commission, a non-departmental public body reporting to the Department for Culture, Media and Sport. Northern Ireland is outside the Act and runs under its own legislation; a GB-licensed bookmaker is licensed to take bets in Great Britain, not in Northern Ireland.
A second regulator sits alongside the Commission: the Financial Conduct Authority regulates financial spread betting — the product a punter places on indices, currencies, commodities and shares — through a separate licence regime. Sports spread betting offered by a bookmaker is a Commission product. Both regulators keep a public register.
Since the Gambling (Licensing and Advertising) Act 2014, an operator whose remote facilities are used in Great Britain needs a Commission licence wherever the operator is based. Sections 33 and 36 of the Gambling Act 2005, as amended, set this out. A Curaçao, Maltese or Gibraltar licence alone is not a substitute; an operator without the Commission licence that takes bets from UK customers commits the offence under section 33 — on summary conviction, up to 51 weeks’ imprisonment, a fine up to level 5, or both (six months in Scotland). Providing gambling facilities in Great Britain without the licence the Act requires is the offence; the customer is not the offender.
There is no state-set cap on stakes, no list of permitted bets and no state monopoly. The state hands out licences, and the Commission enforces them. Operators decide what to offer, who to accept, what limits to set and what markets to price.
Identity verification has been a Commission requirement since 7 May 2019. Before a customer can deposit or gamble — including with a free bet or bonus — name, address and date of birth are checked against the operator’s records. The first bet a punter places, free or paid, is behind an identity check. There is no anonymous play at any of the ten operators in this guide. Credit cards are banned for gambling (since 14 April 2020, LCCP condition 6.1.2), including payments funded through an e-wallet that is itself topped up by credit card; debit cards and bank-based payments are not affected.
The Commission has tightened player-protection rules in two stages. A financial vulnerability check (LCCP 3.4.4), in force since 30 August 2024 and applied at the operator’s threshold since 28 February 2025, kicks in once a customer’s net deposits (deposits minus withdrawals) cross £150 in a rolling 30 days. It is a public-record check — bankruptcy, county court judgments — not a credit reference check and not an income check. Financial risk assessments, often called “affordability checks”, were announced in a Commission article of 7 July 2026 with a staged plan and no start date; the honest framing is “announced, staged, no start date”, not “in force”.
Deposit limits are also rolling out in two phases. The first changes have applied since 31 October 2025; a second phase was postponed to 30 September 2026. Whether the second phase is live on the date a punter is reading this is not established from the public record; the right framing is to describe the rules that are in force and stop there.
A licensed bookmaker in Great Britain takes part in GAMSTOP, the national multi-operator online self-exclusion scheme. The condition has been mandatory since 31 March 2020. A punter who registers on GAMSTOP is barred from every licensed online operator’s site and app. Self-exclusion periods are six months, one year, five years or five years with auto-renewal; after the minimum period runs out, the exclusion stays in place for a further seven years unless the customer asks GAMSTOP to take it off. A financial spread betting account is on a separate scheme run by the FCA — the same idea, but a different provider.
General Betting Duty is the operator’s tax, currently 15% of gross profits on most UK betting. From 1 April 2027 a new remote betting rate of 25% applies to remote bets other than UK horse racing, self-service betting terminal bets and pool betting. Spread betting has its own rates — 3% on financial spread bets, 10% on other spread bets — and the duty is the operator’s, not the player’s. The punter pays no tax on betting winnings; a professional gambler should ask HMRC or an adviser.
Bonus terms changed on 19 January 2026. Wagering requirements on bonuses are capped at 10x (a £10 bonus with a 50x wagering factor previously required £500 of bets; the cap drops that ceiling to £100). Mixed-product promotions — an offer that requires gambling on two or more product types, for instance a free-spins offer gated on a football bet — are banned. Whether the cap applies to free bets with no wagering condition, and any cap on the money value of a bonus, are not established; the rule as stated governs any bonus with a wagering factor.
Advertising runs through the Committees of Advertising Practice — the CAP Code for non-broadcast and the BCAP Code for broadcast — enforced by the ASA. CAP section 16 says marketing must be socially responsible, must not be of strong appeal to under-18s, and no one who is or seems to be under 25 may feature gambling or play a significant role (with an exception for marketing placed where a bet can be made directly). The rule concerns who may appear in an advertisement; it does not set a betting age. The minimum betting age at any Commission-licensed operator is 18.
“Whistle-to-whistle” is an industry code, not law. Since 1 August 2019 betting advertisements are not shown on TV from five minutes before a live sporting event to five minutes after it, before the 9pm watershed. Horse racing and greyhound racing are excluded. The Premier League clubs’ withdrawal of front-of-shirt gambling sponsorship from 2026/27 is voluntary, not law; sleeves and hoardings remain.
Offshore. A Curaçao- or Malta-licensed bookmaker that takes bets from UK customers without a Commission licence is committing an offence under section 33 of the 2005 Act. The enforcement route is disruption, not ISP blocking — cease-and-desist notices, search-engine referrals, work with registrars, hosts and payment providers. The Commission has been given or is about to receive court-order DNS blocking powers; ISP-level blocking is not in force. A punter who bets on an unlicensed site loses four protections a Commission-licensed site is required to provide: no GAMSTOP coverage, no Commission complaints route, no approved dispute-resolution body, no British consumer redress if funds are withheld. The bonuses on the unlicensed site are not bound by the 10x cap. The £150 vulnerability check does not apply. Verification is usually lighter and source-of-funds questions rarer. The site is not “legal to use” — using it is not the punter’s offence, but the safer framing is “licensed or unlicensed”, not “safe or unsafe”.
The financial spread betting sector is lighter on consumer protection and heavier on professional-client treatment. Spread betting on indices, currencies and commodities is set up for clients who can stomach a margin call; the FCA’s categorisation of clients puts retail punters into a category with mandatory risk warnings and loss caps. Collateral on financial spread bets is typically 5–10% of total exposure, and losses are not capped by a single stake.
UK spread betting is licensed, checked, advertised under named rules and taxed on the operator’s side. The punter is the consumer of a regulated product, not the subject of a regulatory regime. That framing is what the legal frame gives a punter — she has protections, and they apply because the bookmaker is licensed; she has fewer if the bookmaker is not.
Responsible gambling
Spread betting places more risk per bet than fixed-odds betting does. The book’s headline at Spreadex, the only firm in this guide with the dual FCA and UKGC licences, states this directly: “spread betting losses can exceed your deposit”. The statement is from the operator; it is also the honest summary of the format.
GAMSTOP is the front-line self-exclusion tool. A punter who registers is barred from every Commission-licensed online operator in Great Britain — the ten in this guide and every other licensed bookmaker. The exclusion is for six months, one year, five years or five years auto-renewed. After the minimum period a further seven-year hold is the default. A punter who wants the exclusion lifted asks GAMSTOP, not the bookmaker.
A licensed bookmaker also offers a self-exclusion route directly, alongside deposit limits, time-out periods and reality checks. The bookmaker’s self-exclusion is single-firm; GAMSTOP is national. Either path is more effective if the punter takes it before the betting is the problem, not after.
Help is available beyond the licensed bookmakers. GamCare runs the National Gambling Helpline (0808 8020 133). GambleAware funds treatment and information. The NHS runs gambling clinics across the country, and Gamblers Anonymous runs group meetings. None of these is a regulator; all of them are reachable for a punter or a punter’s family without going through the bookmaker first.
Financial vulnerability check and deposit limits are the operator-side rules. A punter who has deposited and withdrawn more than £150 net in a rolling 30 days at one operator can expect a public-record check on bankruptcy or county court judgments. Staged affordability checks (the “financial risk assessments”) have been announced; the start date is not set. Deposit limits are the punter’s choice at the operator, set on whatever fixed time frame the operator offers.
Thearity of a bet. Spread bets are settled at the result, not at half-time or on a closed market. A half-time loss on a football spread that becomes a full-time win is paid as a win; a half-time win that becomes a full-time loss is settled as a loss. The settled loss is what the operator books against the punter’s account, and the punter’s account must cover the loss. A licensed operator does not allow a negative balance to grow beyond the credit limit; an unlicensed one might. The format’s risk on a single bet is bounded at deposit level — the punter’s loss is limited to the account balance — and unbounded at outcome level, because a worst-case spread on a single fixture is the whole of the deposit.
A spread bettor who treats the format like fixed-odds betting gets hurt. A spread bettor who sizes positions to a small percentage of bankroll and stops on a daily loss limit survives longer. The rules of bankroll management are the same as in any other form of trading: small position size, fixed maximum loss per session, no bet under emotional stress, time-out after a losing streak.
A punter whose betting is no longer fun is a punter who should stop. A punter who is chasing losses, betting more than she can afford or borrowing to bet is a punter who has crossed a line. The lines are easy to describe and harder to see from inside.
How a winning bet pays back
A working example shows the bookmaker’s margin in cash terms. The illustrative two-way market is priced at decimal odds 1.90 / 1.90 (fractional 9/10 each side). One side wins the stake times the decimal price (a £10 stake at 1.90 returns £19 — £10 of stake and £9 of winnings), the other side loses the £10 stake. The implied probability on either side is 1 ÷ 1.90, or about 52.63%. The two probabilities sum to 105.26%, and the bookmaker’s margin is 5.26%. That margin is the book’s fee on the bet; the punter’s expected return across both outcomes is 94.74% of stake, and the bookmaker’s expected take is 5.26%.
That is the band the punter is pricing against. The illustrative 5.26% margin sits on a single fixture at a single bookmaker. Tournament events — Premier League, Champions League, Grand National — will run closer to a 4% margin on the most-bet fixtures. Off-piste events run wider. Spread bets on Total Goals sit on the lower end (the bookmaker is confident on the totals market), and exotic markets — the punter on a non-runner in a horse race, a corner-count market on a Tuesday night League Two fixture — sit on the upper end. The exact margin depends on the event, the firm and the snapshot. The pricing structure is the same.
The closing line is the right band, not the headline. A spread bookmaker’s margin is the gap between buy and sell; the punter’s cost of betting is half that gap. A wider spread is a larger fee. A tighter spread is a smaller fee. The bookmaker’s margin on a 1.90 / 1.90 market is 5.26%, on a 1.95 / 1.95 market is 2.56%, on a 2.00 / 2.00 market is 0%. A 2.00/2.00 is a fair coin-flip and a bookmaker would not post one; the band is what the bookmaker’s fee looks like in cash terms on a single bet.
A spread punter can check a bookmaker’s margin by reading the spread’s buy and sell, converting to a midpoint, and comparing the midpoint to a true no-margin price. A 0.2 spread on a Total Goals line with a midpoint of 2.7 means a fee of roughly 0.1 goals on either side; on a 2.7-goal over/under that is a margin of about 3.7%. That check is mechanical. It is also exactly what the bookmaker’s fee on the bet looks like.
The arithmetic is the same on every product. The bookmaker’s margin is the gap between buy and sell. The punter’s effective cost is half that gap. A punter running positions on the major tournaments will see tighter margins than a punter running positions on the off-piste fixtures. The price a punter sees on screen is the bookmaker’s view of the event, and the bookmaker makes money when the price is wider than the true probability distribution would suggest.
Frequently asked questions
What is sports spread betting?
A wager where the payoff grows with how accurate the bet is, not with a simple win or lose. A punter buys or sells a number — Total Goals on a football match, runs on a cricket innings, finishing distance on a horse race — and the winnings or losses are the difference between the result and the bet level, multiplied by the stake per unit of distance. Losses can exceed the original stake.
How does spread betting work on football?
The bookmaker publishes a spread on Total Goals and Supremacy. A 2.6–2.8 Total Goals spread means the punter buys at 2.8 (bets more goals) or sells at 2.6 (bets fewer). A £2 stake at 2.8 returns £0.40 for every 0.1 goals above 2.8, and pays out the difference between the final goals total and 2.8 times the £20-per-unit distance.
What is sport spread betting at a UK bookmaker?
A regulated product on a Gambling Commission-licensed site, where the punter bets the accuracy of a number — Total Goals, Supremacy, Race Index — rather than a winner. Spread bets on financial products are regulated separately by the Financial Conduct Authority.
How can a punter check a bookmaker holds a Gambling Commission licence?
The Commission’s public register is searchable by business name, trading name, domain or account number. The register lists the licensee, the licence categories held, any regulatory action and the current status. The register is the only test of whether a brand holds a current licence.
How is the return on a bet worked out from the stake and the odds?
For a fixed-odds bet, return equals stake times decimal odds; net profit equals stake times (decimal odds minus one). For a combination bet, the odds of the legs multiply into one price. A £10 stake at 4.50 returns £45 (£10 of stake and £35 of winnings).
What is the bookmaker’s margin and how does it show in the odds?
The margin is what the bookmaker keeps of every unit bet on a market. The implied probability of each outcome (1 / decimal odds) sums to more than 100% across the market, and the surplus is the book’s margin. A 1.90/1.90 market has a margin of 5.26%; the punter gets back, on average, 94.74% of every pound staked.
Betting sites & exchanges – signupbetsguide.com
Content created by the «signupbetsguide.com» team
